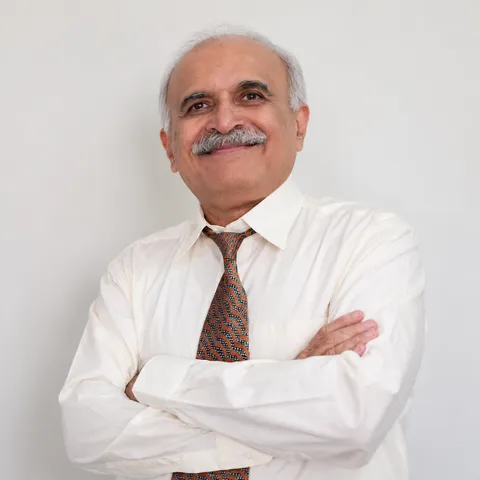
Anil Dadlani
5.0 from 28 Google reviewsMortgage Choice Anil Dadlani · Craigieburn, VIC
Website verified
ConstructionPAYGFirst home buyersCommercial
Compare mortgage brokers in Melbourne who help first home buyers. Check their BrokerScore and reviews, and see which lenders they work with.
These mortgage brokers haven’t listed first home buyer as a specialty on BrokerScore. Many still help with it, so it’s worth asking.
General information only, last checked 9 October 2026. Grants and concessions change often and have eligibility rules, so confirm with the official source or a mortgage broker before you rely on them.
A broker works out how much you can borrow, compares loans across their lender panel, checks which grants and schemes you qualify for, and manages the application through to settlement. Most are paid a commission by the lender, so you usually don’t pay them directly. Ask them to explain how they’re paid before you start.
Lenders will want ID, recent payslips, bank statements showing your savings history, details of any debts (including credit cards and buy now pay later), and your last tax return if you’re self-employed. Having these ready speeds up pre-approval.